The 401(k) and the match
What it is: a workplace retirement plan. Contributions come out of your pay before you see them, which is most of why it works.
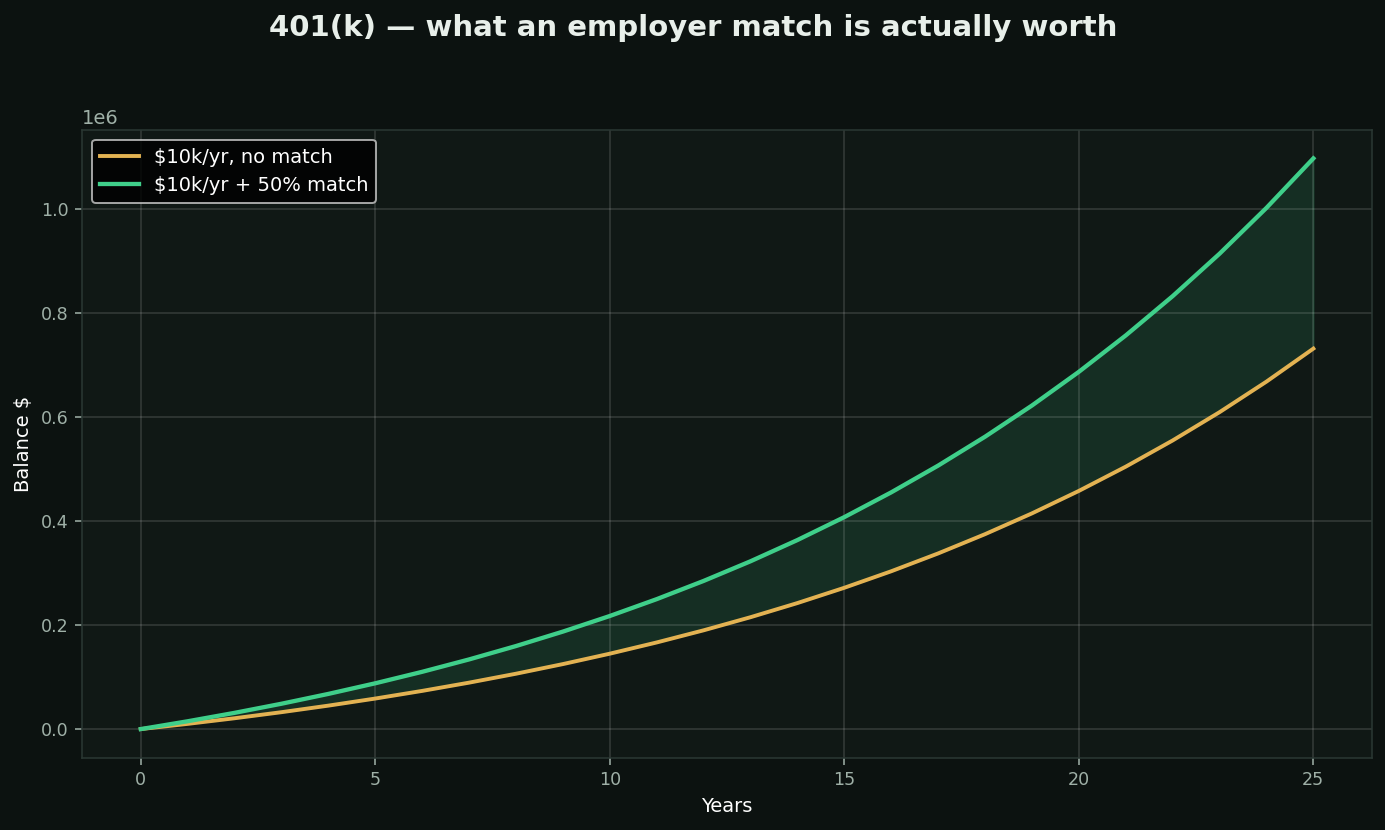
The match is the whole story. An employer matching 50% of your contribution is an instant 50% return, before the market does anything. There is no investment that reliably competes with that. Not capturing the full match is leaving salary on the table.
Mechanics worth knowing:
• Vesting — the match may not be yours until you have stayed a set number of years. Check the schedule before you resign.
• Many plans now offer a Roth 401(k) — same account, opposite tax treatment, and no income limit to use it.
• Fund choice matters: see the lesson on expense ratios.
Chart: identical contributions, one with a 50% match. Same market, same discipline, very different ending.