Sequence of returns risk
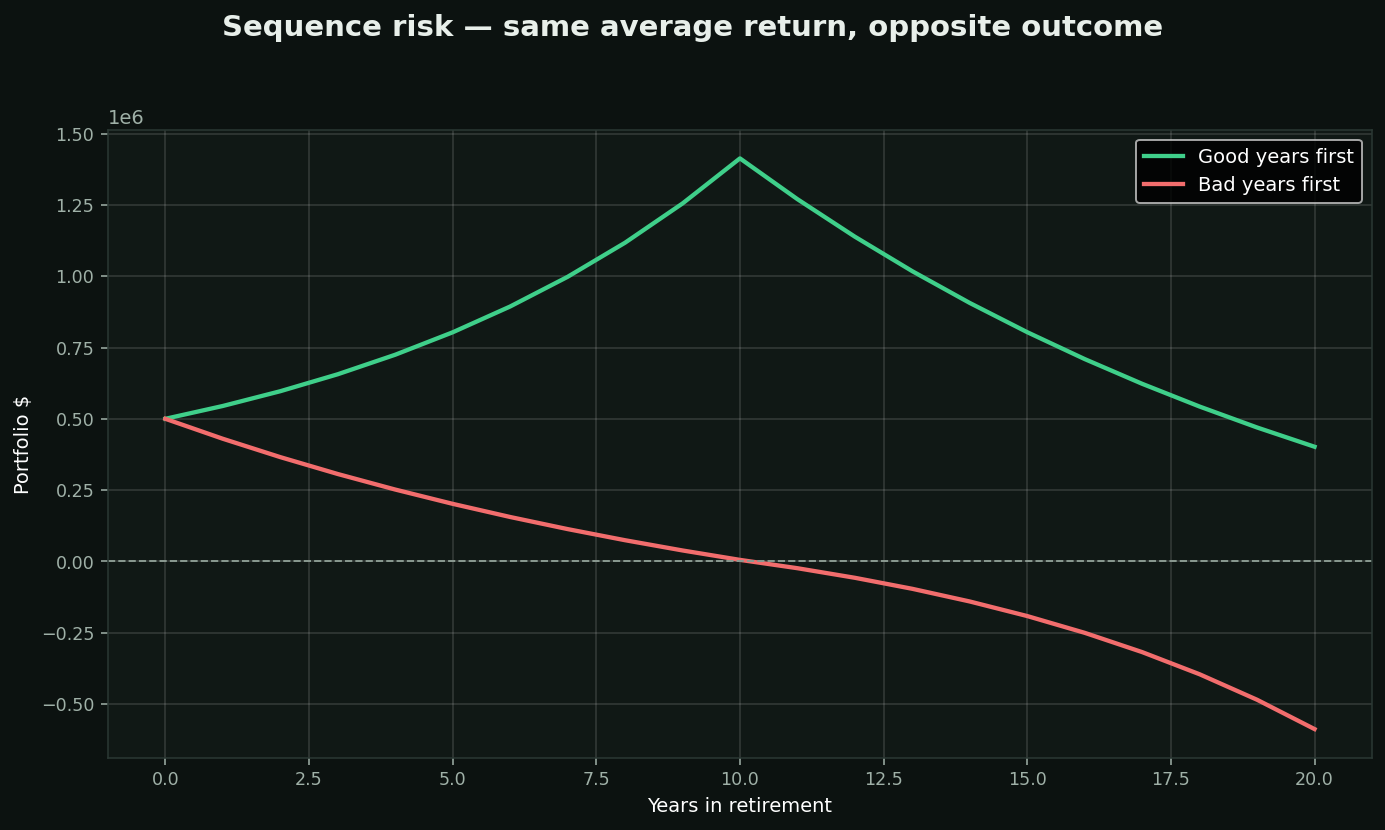
The idea: when you are withdrawing, the ORDER of returns matters as much as the average. Two retirees with identical average returns can end up in completely different places.
Why: a loss early in retirement is taken on a large balance, and you are also selling into it to fund living costs. Those shares are gone and cannot recover. The same loss later lands on a smaller balance after years of growth.
While you are still saving, this works in reverse — an early crash is good for you, because you buy cheaply for years.
How people manage it:
• Hold one to three years of spending in cash so you never sell into a decline
• Reduce equity exposure approaching retirement, then raise it again
• Flexible withdrawals — spend less in bad years
Chart: identical returns, reversed order, $30k withdrawn yearly.